
Mortgage professionals exist in a market where factors like context, speed, and test affect almost each borrower’s interaction. A buyer can ask for preapproval in the morning, interact with an agent during lunch, compare options for that event, and anticipate a response the before the next day starts. A crowded inbox and spreadsheet support this pace rarely.
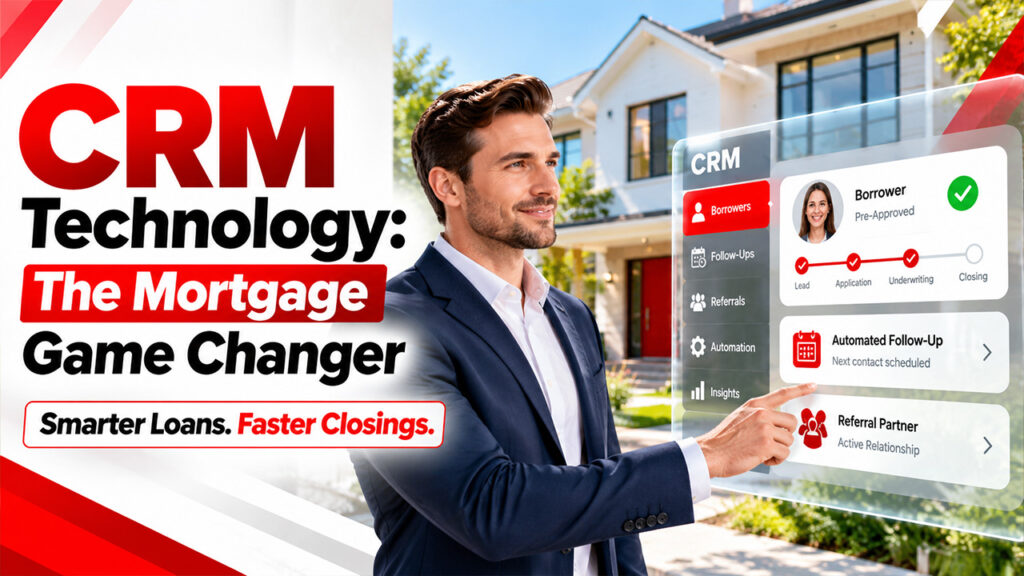
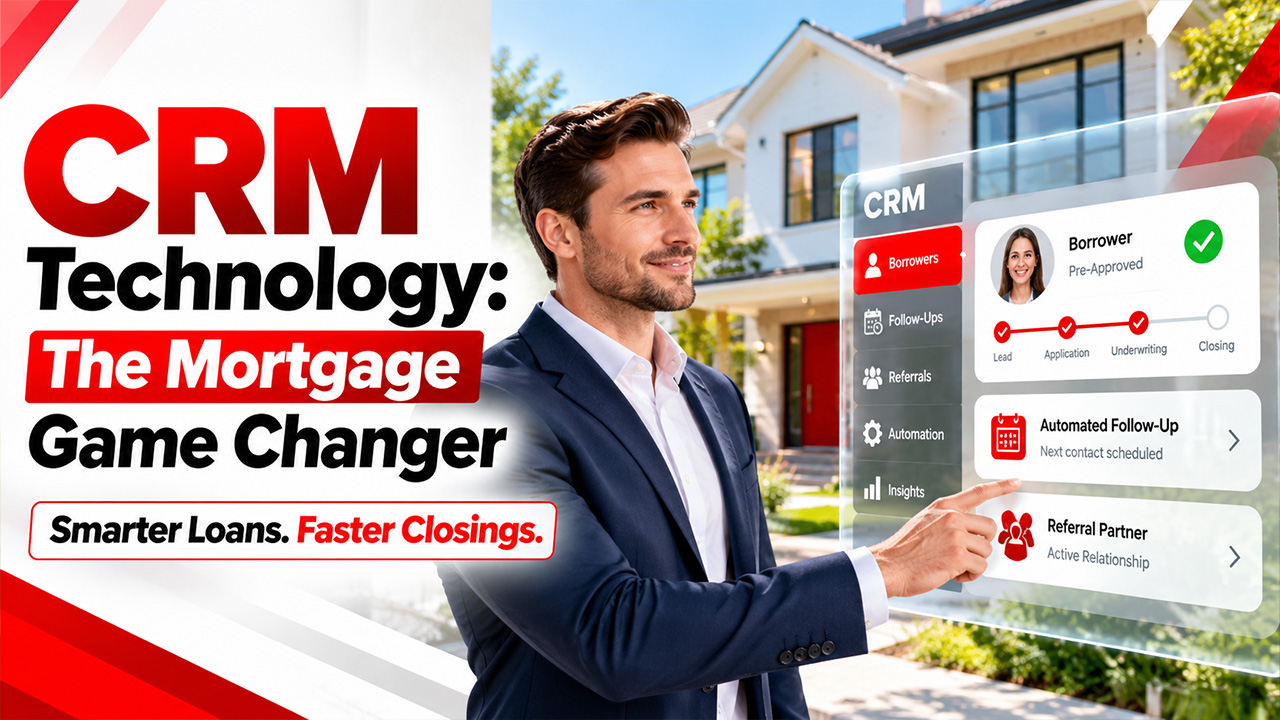
Customer relationship management software provides loan provide an organized way to keep track of people, tasks, conversations, follow-up dates, and referral partners. Good mortgage CRM software enables a professional to remember what is important, respond at the right time, and make sure that every borrower moves without making every interaction seem like a manual admin work.
For a customer that looks for home loan broker in Tennessee, technology may mostly remain invisible. What the borrower notices is very simple: fewer repeated questions, faster replies, and communication that showcase details that are shared already. This experience typically begins with the systems that drives the loan officer.
CRM Is Moving From Contact Database to Daily Workflow
Older CRM setups often acted like digital address books. Modern mortgage teams require more. A helpful platform can sort leads as per the stage, assign reminder tasks, store history of communication, connect referral sources with results, and show where a borrower requires attention.
Mortgage typically does not follow a predictable and linear sequence. One client may pause while improving credit. Another may require a preapproval on the same day before you submit an offer. A third one may come after a year. Without having a consistent record, the context disappears.
Automation Must Manage Repetition, Not the Entire Relationship
Automation is an effective choice on predictable tasks which include appointment confirmations, reminders, status messages, document requests, and scheduled check-ins. It must not make each borrower seem like the same person.
Loan officers still need to make decisions when a call makes more sense than an email, when a borrower requires an explanation in simple language, and when a referral partner requires an update. Perhaps the rule is quite straightforward: automate repetitive tasks so humans get more time for judgement.
CRM and Loan Origination Systems Serve Different Jobs
The CRM systems manage relationships before, during, and even after a transaction is completed. The loan origination system, or LOS, generally manages the mortgages file and operational steps that are required to process the loan. They usually overlap but also solve different problems.
When data moves safely between the two systems, the team manages to reduce duplicate entry and gain a clearer view of borrower progress. A loan officer can also see that a lead has become an application or that the follow-up matters now. Done badly, the same connection can also create stale fields, duplicate records, or unnecessary access to sensitive information.
Data Quality Determines Whether Automation Helps
A workflow is only considered reliable as the data that is triggering it. If a CRM platform contains an old phone number or duplicate contacts, it can create errors.
Teams should also define who owns each field, especially when records get updated, and which event trigger communication. Short rules beat vague ones. Someone must know what “preapproved,” “application started,” and “inactive” mean inside the system.
Technology Can Improve Agent and Referral Partner Communication
The mortgage professionals usually do not work alone. They work with real estate agents, processors, title professionals, and other parties that need updates at different points.
A CRM platform can help a loan officer remember key points, such as referrals sources, track partner conversations, schedule post-closing outreach, and also avoid losing contact after one transaction. The main value is consistency, and not spam.
The borrowers also notice response quality before they understand a lender software stack. Clear explanations and organized follow-up also create a stronger experience.
Security Has to Be Part of the CRM Decision
The mortgage teams also handle sensitive financial information, for which selecting a CRM platform cannot only focus on sales features. The Federal Trade Commission says that its Safeguards Rule covers financial institutions that include mortgage lenders and mortgage brokers. Covered firms should also maintain an information security program that is designed to protect customer information. The rule also addresses access controls, encryption, multi-factor authentication, service-provider oversight, and other safeguards.
Teams should ask who can access borrower records, whether the vendor supports role-based permissions, how it protects data in transit and at rest, what happens when an employee leaves, and which third-party tools can pull information from the system.
For someone researching the best mortgage lenders in Nashville, those controls may not appear on a comparison page. They still matter. Mortgage professionals handle data that borrowers reasonably expect them to protect.
Compliance Settings Need Human Ownership
The software is a tool that assists with organizational policies but it is not accountable for those policies. The staff are required to specify which employees enter the system and they examine who has permission to view data - those employees teach the staff members plus they observe the companies that provide services. They determine the duration of time that data stays within the database.
A CRM sends a communication because a programmed instruction commands the action - but the employees must evaluate if that instruction aligns with legal statutes and the internal rules of the company. The staff verify that the message matches the agreement of the borrower but also the specific circumstances of the interaction.
AI Is Adding a New Layer to Mortgage CRM
AI features now appear across sales and customer-service software. Useful cases for loan officers are often modest: summarizing notes, drafting follow-up messages, identifying unanswered conversations, or helping staff search records faster.
The risk starts when teams treat generated output as verified financial guidance. Mortgage scenarios depend on borrower facts, program rules, lender requirements, and timing. AI can help organize information. Licensed professionals still need to review advice and confirm what applies.
The strongest system will make human review easier, not hide it.
AI Is Entering the Mortgage CRM Space
We are working on a wide range of AI capabilities integrated into sales and customer-service tools. Loan officers' most practical use cases tend to be fairly simple - like digesting notes, automating follow-up messages, flagging unresponded-to conversations, or assisting staff in searching records more quickly.
The danger begins when teams view what is generated as accurate financial advice. Each mortgage scenario is based on a borrower's specific data, program guidelines, lender conditions and timing. AI can be used to organize this data. But licensed experts must still verify recommendations and validate applicability.
The best system will make human review more straightforward, not obscure it.
Marketplace Visibility and CRM Address Different Pieces of the Growth Equation
Discover and follow up. Marketplaces can introduce a consumer to a professional, verify their credentials, read about their specialties and get the conversation started. Connect consumers and NMLS-verified loan officers that they can filter by loan type, specialty, spoken language and state.
CRM continues that discovery or does it while things are happening. CRM is the way for the professional to keep managing the relationship when that lead shows up. One system creates visibility. One system will save those opportunities from going to the dead box.
The Better Tech Stack Is Normally Simpler
Mortgage teams don't need the largest gun collection. They need a gun rack their employees will use. Can the loan officer identify the next step on any current prospect? Can the team locate the last essential conversation? Can managers identify the follow-up that was overlooked? Can users regulate who can access private information? Can the referral system accommodate different relationships without spamming everyone?
Final Takeaway
CRM systems offer a formalized approach for loan officers to stay on top of things and reach out to borrowers. They are even more beneficial when your team uses them with clear protocols, precise data, guarded access, and human supervision.
The mortgage industry is built on trust. Software cannot build that trust, but it can make it easier and help a professional to earn the trust of the homebuyer through intelligent, effective communication.